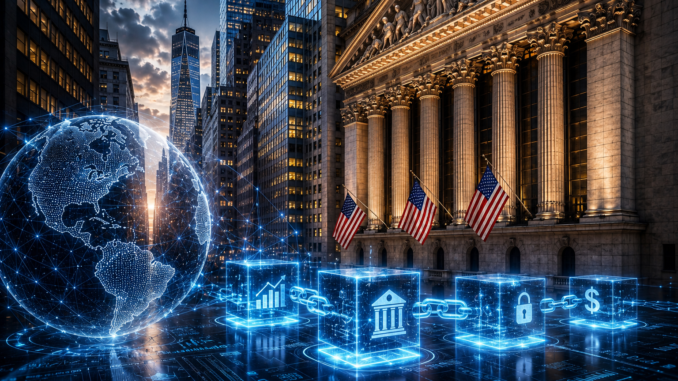
The Quiet Revolution Reshaping U.S. Stocks
A regulatory framework, a planned 24/7 NYSE platform, and the slow rewriting of how America buys and sells its own equities. A particular kind of silence tends to accompany the market-structure shifts that actually matter. It attended the rise of exchange-traded funds in the early two-thousands. It followed high-frequency trading a decade later. It is here again in the unflashy tokenization of U.S. equities. No new coin, no meme rally — and, for any retail investor, regulator or bank treasurer paying attention, considerably more consequential than the headlines admit.
What “Tokenized Stocks” Actually Are
A tokenized stock is a blockchain-based representation of a share in a publicly listed company. The underlying asset — say, a share of Nvidia — still sits with a regulated custodian, broker or transfer agent. The on-chain token is a tradable digital mirror of it: fast to move, easy to fractionalize, and programmable enough to plug into lending, collateral or automated settlement flows. Two flavors matter. The first is issuer-sponsored, where the company itself, or a transfer agent working for it, issues digital shares on a blockchain. The second is third–party sponsored, where a custodian, crypto exchange or fintech wraps a traditional share into a token and sells that token to crypto-native users — sometimes around the clock, sometimes without ever granting the holder a real seat at the annual meeting. The distinction is not technical. It is legal. And the U.S. Securities and Exchange Commission has been very clear about what it does and does not change.
The SEC Has Spoken — Quietly, but Clearly
In January 2026, the SEC’s Division of Corporation Finance, Division of Investment Management, and Division of Trading and Markets issued a joint statement on tokenized securities. The substance came down to one line: a tokenized security is still a security. Wrapping a share of Apple in a blockchain-based token does not retire the registration requirements of the Securities Act. It does not exempt the issuer from disclosure. Tokenization does not, by itself, eliminate the legal obligations attached to the underlying security, although the rights afforded to token holders can vary depending on the structure. The Commission has chosen continuity over novelty. The token is a new envelope; the letter inside is the same. What that tells Wall Street is that new rails are welcome, on the existing terms. No parallel universe of unregistered digital shares. No shadow market in “synthetic” tokenized equity.
Two Models, One Question of Trust
The practical consequences land hardest on third-party tokenization. When a crypto exchange mints a token that tracks Nvidia’s price, the holder takes on a risk an ordinary shareholder never does: the credit of whoever issued the token. The share may be perfectly sound while the wrapper around it is not. Issuer-sponsored tokenization looks different. Here the company, or its transfer agent, mints the token on a permissioned or public chain, and the token represents a real record-keeping interest in the share. Depending on the structure, issuer-sponsored tokenization can be designed to preserve or closely track the economic and governance rights associated with traditional ownership. This is the model institutional infrastructure players are quietly betting on.
The NYSE’s 24/7 Bet
Those bets are getting larger. In January 2026, ICE — parent company of the New York Stock Exchange — announced a tokenized securities platform aimed squarely at the U.S. equity market. The proposed platform is designed to enable round-the-clock trading of U.S.-listed equities and ETFs, fractional share trading, instant settlement via tokenized capital, and stablecoin-based funding. Clearing infrastructure is being rebuilt alongside it, with BNY and Citi among the banks working on tokenized deposits so that clearing members can move money at any hour, in any time zone.
The strategic logic is plain. Settlement, currently operating on a T+1 standard for U.S. securities transactions, remains an important source of post-trade infrastructure and operational complexity. On-chain infrastructure could reduce some post-trade friction, enable faster settlement and make assets available for subsequent financial uses more quickly. Continuous trading opens the market to investors who live, work and save across multiple time zones. Fractional ownership turns a four-thousand-dollar share into a fifty-dollar token. NYSE leadership frames this as a marriage rather than a break: the trust of a two-hundred-year-old exchange, the speed of a blockchain. Lynn Martin, president of NYSE Group, has described the aim as using the exchange’s own expertise to “reinvent market infrastructure” for the demands of a digital future.
The Economic Stakes
Look past the technology and the stakes are geopolitical as much as financial. The prospect of a 24/7, on-chain, instantly settling U.S. equity market is an architectural choice about where the world’s savings sit. Tokenized U.S. equities, distributed on rails that a retail investor in Lagos, Manila or São Paulo can reach through a phone, are an export of monetary influence. For the retail investor in Ohio the same shift looks domestic and personal: smaller ticket sizes, faster access, lower fees, and eventually a U.S. stock and ETF portfolio that settles as smoothly as a Venmo payment. For Wall Street it is existential — the back office that has justified a good deal of the industry’s cost base is the part being automated away. It is also a test of trust. A blockchain does not forgive mis-sold tokens or unregistered securities. The investor protections that U.S. equity markets spent a century building — disclosure, registration, the orderly bankruptcy of a listed company — cannot be re-encoded into a smart contract. They live in courtrooms, in regulators, and in the slow-built reputations of brokers and exchanges. If tokenization outruns those protections, what follows will not be a revolution. It will be a financial scandal waiting for the next cycle.
Innovation, Regulation, and the Long Memory of Markets
The SEC’s evolving framework, the NYSE’s bet and the slow build of tokenized rails all converge on the same principle: innovation is welcome, but existing securities obligations remain in force. Whether U.S. stocks will increasingly trade on-chain is no longer a hypothetical question. Major market infrastructures are already building toward that possibility. The interesting question is whether the courts, the exchanges and the regulators can move at the speed of the technology they are trying to govern.
What is being planned is not a single dramatic event but a multi-year repaving of the floor of American finance, around digital settlement, on-chain ownership and round-the-clock execution. It will arrive slowly enough to bore the crypto timelines and fast enough to catch out anyone who has stopped reading the SEC releases. And it implicates almost everyone: the twenty-two-year-old opening a brokerage app at midnight, the sovereign wealth fund settling a billion-dollar trade in seconds. The next chapter of American capital markets is being written here, in policy and in code, with the twentieth-century market still looking over its shoulder.
The views presented in this article are the authors’ own and do not necessarily reflect the views of Global Strategic Forum – GSF.
Imran Bhatti
Imran Bhatti holds an M.Phil. in Governance and Public Policy and professional certifications as a Certified Information Systems Security Professional (CISSP) and Project Management Professional (PMP). He is a geopolitical analyst and writer specializing in energy geopolitics, great-power competition, Eurasian strategic affairs, and South Asian security dynamics. His work explores regional geopolitics, border disputes, infrastructure, security, and economic statecraft in an increasingly multipolar world.
- Imran Bhatti
- Imran Bhatti
- Imran Bhatti
- Imran Bhatti
Leave a Reply