
The Great Rail Gamble: Iran's Audacious Bid to Bypass the Strait of Hormuz
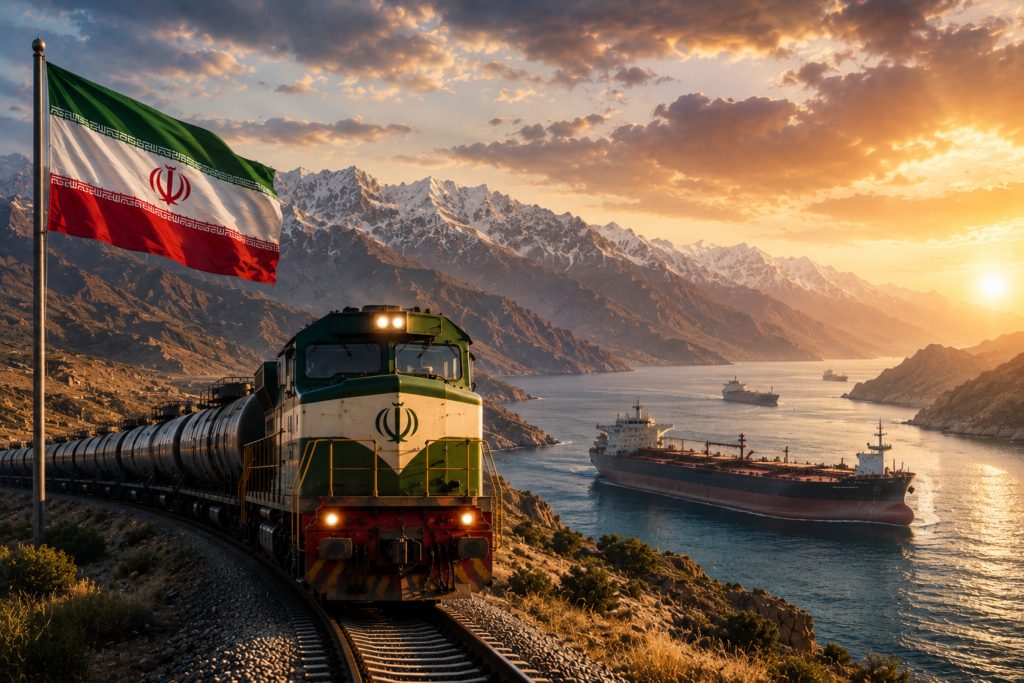
Exploring Iran's strategic efforts to reshape energy routes through rail connectivity, Eurasian partnerships, and alternatives to maritime chokepoints.
When the Sea Becomes a Trap
Picture this: a convoy of Very Large Crude Carriers sitting idle in the Persian Gulf, their hulls gleaming under a merciless sun, while somewhere north of Tehran, a freight train loaded with oil tanker cars begins its slow, defiant crawl toward the Caspian coast. This is not a hypothetical. In May 2026, as naval tensions in the Strait of Hormuz reached their most volatile point in a decade, Iran quietly accelerated one of the most audacious energy strategy pivots in modern geopolitical history — a calculated gamble to move its economic lifeblood from the world's most contested waterway onto iron rails cutting through deserts, mountains, and the Eurasian steppe.
The Strait of Hormuz, that narrow 33-kilometer chokepoint between Iran and Oman, has always been Iran's greatest asset and its most dangerous vulnerability. Roughly 20% of the world's traded oil passes through it daily. For decades, Tehran wielded the implicit threat of closure like a scalpel — precise, terrifying, and rarely used. But in 2026, the calculus changed. A de facto shadow naval blockade, assembled through a combination of U.S. Fifth Fleet repositioning, allied maritime surveillance networks, and coordinated insurance and banking sanctions, began choking Iran's oil exports far more effectively than any formal embargo. Tehran's tankers sat tracked, sanctioned, and increasingly stranded.
So Iran looked north. And it looked east. And it found a railroad.
The Shadow Blockade: Why the Sea Has Become Dangerous
To understand Iran's rail pivot, you must first understand what a shadow blockade looks like in practice. It does not require naval vessels physically blocking a channel. In the hyper-connected financial world of 2026, economic warfare is more surgical. Western-aligned insurance markets have effectively blacklisted Iranian tankers. Port access across Southeast Asia and Europe has tightened under secondary sanctions threats. Ship tracking networks identify "dark fleet" vessels those that disable their AIS transponders within hours.
The result is that while the Strait of Hormuz technically remains open, Iranian oil struggles to find buyers, carriers, and banking pathways through it. Officially, Iran exported somewhere between 1.5 and 1.8 million barrels per day (bpd) in late 2025, predominantly to China through complex gray-market arrangements. But the friction costs discounts, rerouting fees, sanctions risk premiums were bleeding the Iranian treasury. Every tanker that loaded at Kharg Island was rolling the dice on whether it would reach its destination or end up seized, sanctioned, or simply refused.
This is the strategic wound that Iran's rail gamble is designed to bandage, if not fully heal.
Iran's Rail Gamble — The Architecture of a Bold Plan
Esfahan: The Industrial Heart of the Pivot
At the geographic and logistical center of Iran's plan sits Esfahan, the country's industrial powerhouse and a critical node in its national rail network. Home to Iran's largest steel mills, oil refineries, and manufacturing complexes, Esfahan is not simply a waypoint — it is the engine room. Pipeline infrastructure connecting southern oil fields to Esfahan's refining capacity provides the first link in a chain that Iran hopes will eventually bypass maritime chokepoints entirely. From Esfahan, rail lines extend both north toward the Caspian corridor and northeast toward Mashhad.
The Caspian Oil Swap Mechanism
Iran's most immediately actionable move is the so-called "oil swap" arrangement with Russia through the Caspian Sea. The mechanics are elegant in their simplicity: Iran delivers crude oil to ports on its northern Caspian coastline primarily Neka where it is loaded onto smaller Caspian-class tankers (the Strait is inaccessible to VLCCs). Russia accepts this oil at its southern Caspian ports, integrates it into its own pipeline network, and delivers equivalent volumes of Russian crude to Iranian-designated buyers in European or Asian markets, minus a handling fee.
This arrangement sidesteps the Persian Gulf entirely. It leverages Russia's existing pipeline infrastructure including the Baku-Novorossiysk line and connections to the Transneft system and turns Moscow into a complicit middleman and strategic partner simultaneously. For Russia, still navigating its own Western sanctions post-Ukraine, the arrangement offers transit fee revenue, strategic depth with Tehran, and a demonstration that the Global South can build parallel financial and energy architectures.
The rail component feeds this swap: oil and refined products moving by train from central and southern Iran to Caspian port facilities, reducing dependence on pipeline capacity that itself faces maintenance constraints under sanctions.
The Iron Silk Road: Mashhad–Sarakhs and the BRI Connection
The second, more ambitious prong of Iran's rail strategy points east. The Mashhad–Sarakhs rail corridor, connecting Iran's second-largest city to the Turkmenistan border, is Iran's gateway into the vast Central Asian rail network and, ultimately, into China's Belt and Road Initiative (BRI) infrastructure. This route runs through Sarakhs a border town that sits at the intersection of Iranian, Turkmen, and Afghan rail gauges and connects onward through Turkmenistan and Kazakhstan into China's western rail terminals. The significance is enormous in theory. China's BRI has invested heavily in transcontinental rail capacity, and Beijing has made no secret of its desire for overland energy supply routes that bypass vulnerable sea lanes. If Iran can move oil and gas by rail to Chinese buyers without a single tanker passing through the Strait of Hormuz or the Malacca Strait, it fundamentally alters the leverage equation with Western maritime powers.
Iran has also been pushing for expanded rail connectivity through its International North-South Transport Corridor (INSTC) commitments a 7,200-kilometer multimodal route connecting Mumbai to Moscow via Iranian territory. The rail segment through Iran is the missing capstone of this corridor, and Tehran has been accelerating construction of missing links, particularly the critical Rasht–Astara connection that would complete the Iranian leg of the route.
The Geopolitical Triangle: Iran, Russia, and China
Each player in this Eurasian energy triangle has a distinct but complementary motivation.
- Iran needs revenue, sanctions relief by proxy, and strategic alternatives that reduce its vulnerability to Western maritime pressure. The rail network is both an economic lifeline and a geopolitical insurance policy.
- Russia gains a sanctioned partner whose energy flows it can manage and monetize, a demonstration of Eurasian bloc cohesion for global audiences, and additional leverage in its ongoing confrontation with the Western-led international order. Moscow also benefits strategically from any architecture that legitimizes parallel financial systems outside SWIFT and dollar-denominated trade.
- China is the most calculated player. Beijing wants Iranian oil at heavily discounted prices which sanctions reliably deliver — while simultaneously building the infrastructure and precedents for an energy supply chain that is immune to U.S. naval dominance. China's investment in BRI rail capacity across Central Asia is not merely economic; it is a long-term hedge against the scenario where American sea power restricts Chinese energy imports during a future Taiwan crisis or broader confrontation.
Together, these three powers are not simply building a railroad. They are constructing the skeletal framework of an alternative global order one where land power, Eurasian geography, and shared sanctions exposure bind their interests together more tightly than any formal alliance treaty.
The Capacity Reality Check
Here is where strategic ambition collides with arithmetic and the numbers are sobering.
A single Very Large Crude Carrier (VLCC) transports approximately 2 million barrels of oil per voyage. Iran's conventional maritime export capacity, even under pressure, can theoretically move 2–3 million bpd through the Gulf. Now compare this to rail:
- A standard oil tanker railcar carries approximately 700 barrels
- A full freight train of 100 such cars carries roughly 70,000 barrels
- Moving 500,000 bpd by rail alone would require approximately 7,000 loaded railcar movements per day
- Iran's current national rail freight capacity handles roughly 50–60 million ton-kilometers annually a figure that would need to increase by an order of magnitude to absorb even a fraction of current oil export volumes
The Caspian oil swap is similarly constrained. Caspian-class tankers carry 12,000–14,000 deadweight tons a fraction of VLCC capacity. The Neka terminal, even after recent upgrades, can handle perhaps 100,000–150,000 bpd under optimal conditions.
The Mashhad–Sarakhs corridor faces gauge incompatibility issues Iran uses standard gauge (1,435mm) while parts of the Central Asian network use Russian broad gauge (1,520mm) requiring transloading or bogie exchange operations at every border crossing. These handoffs are slow, expensive, and create bottlenecks that cap throughput severely.
The bottom line: Even under the most optimistic projections, Iran's rail and Caspian swap mechanisms can realistically supplement, not replace, maritime exports. Analysts estimate a realistic ceiling of 300,000–400,000 bpd through combined northern land routes by 2027–2028 approximately 20–25% of peak maritime export capacity.
This is not nothing. In a constrained sanctions environment, 300,000 additional bpd flowing to China or through Russian intermediaries represents billions in annual revenue. But it is not a strategic escape from maritime vulnerability. It is a partial hedge.
Broader Implications: Markets, Pakistan, and the New Great Game
The ripple effects of Iran's northern pivot extend well beyond Tehran's treasury.
Global Oil Markets: Any successful diversification of Iranian exports through non-maritime channels adds supply resilience for China and Russia while reducing the price premium that Western sanctions impose. For global markets, it is a modestly deflationary pressure on sanctions effectiveness — a signal that the architecture of economic coercion is becoming more porous. Pakistan and the CPEC Question: Iran's energy pivot has uncomfortable implications for Islamabad. The China-Pakistan Economic Corridor (CPEC), anchored at Gwadar port, was conceived partly as an alternative energy transit route for China importing Gulf oil overland rather than through the Malacca Strait. If Iran develops viable Eurasian rail corridors that deliver oil to China more cheaply or securely, Pakistan's strategic value as a transit hub diminishes. Gwadar's promise has always been contingent on no better alternative existing. Iran's rail gamble threatens that assumption.
The U.S.–China–Russia Rivalry: For Washington, the emergence of a functioning Eurasian energy corridor outside Western financial and maritime control is a significant strategic challenge. It demonstrates that sanctions regimes have a ceiling — that sufficiently motivated states, with sufficiently large partners, can build around them over time. This has implications not only for Iran policy but for any future sanctions campaign against China, India, or other major economies.
Risks, Vulnerabilities, and Countermeasures
Iran's railroad is not invulnerable. Consider the exposed points:
- Infrastructure Targeting: Rail lines, unlike ocean routes, are fixed and mappable. In any military escalation, Iran's northern rail corridors would be among the first targets for adversary airpower or covert sabotage.
- Turkmenistan's Reliability: The Mashhad–Sarakhs corridor depends on Ashgabat's cooperation. Turkmenistan, perpetually cautious about its neutrality, has historically proven an unreliable transit partner when geopolitical pressure intensifies.
- Financing and Maintenance: Sanctions limit Iran's ability to procure modern rolling stock, track-laying equipment, and signaling technology. Chinese-supplied alternatives exist but come with their own dependency costs.
- Russian Conditions: Moscow's role as Caspian intermediary gives it significant leverage over Iran — the same leverage it has historically exercised over Central Asian energy producers. Iran risks trading one form of external dependence for another.
Conclusion:
Masterstroke, Survival Tactic, or Historical Signal?
Iran's rail gamble is all three, depending on the time horizon you choose.
In the immediate term 2026, it is a survival tactic: a creative, impressively executed partial solution to a severe problem. It keeps revenue flowing, demonstrates strategic resilience to domestic audiences, and signals to China and Russia that Iran is a serious infrastructure partner worth investing in.
In the medium term through 2028–203, its success depends entirely on whether the INSTC missing links get built, whether Chinese financing materializes at scale, and whether the Eurasian bloc maintains the political will to sustain the arrangement under Western pressure. These are not certain outcomes.
In the long term, Iran's rail pivot may be remembered as one of the early structural moves in a profound reordering of global logistics the moment when Eurasian land power began seriously contesting the five-century maritime dominance of Western-aligned sea powers. The railroad through the desert may seem modest today. But so did the first container ship.
The question for 2030 is not whether Iran can replace the Strait of Hormuz with a railway. It cannot. The question is whether it can build enough of an alternative infrastructure to ensure that threatening to close the strait or having it closed by others is no longer an existential sentence. On that narrower, more achievable objective, the great rail gamble may yet pay off.
The iron wheels are turning. The world should be watching.
The views presented in this article are the authors’ own and do not necessarily reflect the views of Global Strategic Forum – GSF
Copyright © 2026 by GSF Team
Comments
0No comments yet. Be the first to comment.